Wildfire home inventory for your insurance claim
What you get without a list after a total loss, and the phone video that helps you claim the rest.
What happens after a total loss
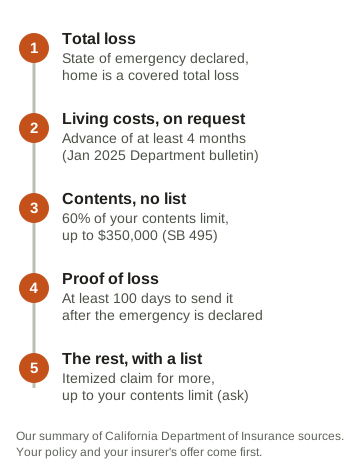
- Contents, no list. SB 495 requires 60% of your contents coverage limit, capped at $350,000, with no detailed inventory [1].
- Time to send proof of loss. At least 100 days after a state of emergency is declared [1].
- Living costs. In its January 2025 bulletin, the Department said an insurer must, on request, advance at least four months of living expenses after a total loss tied to a state of emergency [3].
- The rest. Under the earlier 30% rule, the Department said you could recover more, up to your contents limit, by filing a claim under your policy, and that your insurer had to tell you [3]. We expect the same applies now. Ask your insurer.
The 60% is a share of your contents limit, not of what you owned. If your belongings were worth more than that share, a list is how you would claim the difference. That part is our reading of the rules above.
Make a phone video of your home
The Department tells people to make a photo or video inventory if time allows, and says it can be done quickly on a smartphone and stored in the cloud [4]. Do it on a calm day, not an evacuation day. For a small home, allow about 10 minutes (our estimate). Our tips:
- Walk room by room, slowly. Say what you see out loud: "Samsung TV, 2022, about 55 inches."
- Open everything. Closets, drawers and cabinets hold more than you remember.
- Film labels on big items. Appliances, tools and electronics have model numbers.
- Don't skip the garage and yard. Tools, bikes, patio furniture and the shed add up.
- Save it off the property. Upload the video and a copy of your policy to the cloud [4].
- Redo it when you buy something big. A new video each year is plenty.
In Sonoma County? The Sonoma County go bag checklist covers the papers to grab on the way out.
Ask your insurer this week
- Get your full policy. The Department says the law requires your insurer to give you a copy free within 30 days of your request [4].
- Know three numbers: coverage to rebuild or repair, for your belongings, and for living expenses [4].
- Ask how a contents payment without a list works on your policy, and whether your home would qualify. The Department's 2025 bulletin described the earlier rule as covering a furnished primary home after a covered total loss [3].
Common questions
I saw 30% somewhere. Which is right?
The January 2025 bulletin described the law then in force: at least 30% of the dwelling limit, up to $250,000 [3]. SB 495 sets 60% of the contents limit, up to $350,000, from January 1, 2026 [1][2]. Ask your insurer which applies to your policy.
Do I still need an inventory?
Not to get the first payment. To claim more than that, you would file a claim with a list. Ask your insurer how that works on your policy.
Where is the Department's own guide?
The Department says you can download a free home inventory guide at insurance.ca.gov, or call its consumer line at 800-927-4357 [4].
What it means for you
- Take the video this weekend. A list is slow to rebuild after a loss.
- Put your policy in the cloud too.
- Know your contents limit, so you know what the 60% would be.
- Worried about keeping your coverage? That is a different problem, and it comes first.
Sources
- California Department of Insurance, "Commissioner Lara Applauds Governor's Signing of New Consumer Protections for California Wildfire Survivors," October 10, 2025.
- California Department of Insurance, "New laws sponsored by Commissioner Lara ... take effect January 1," December 30, 2025.
- California Department of Insurance, Bulletin 2025-2, "Wildfire Consumer Protections and Advanced Payments," January 23, 2025 (PDF).
- California Department of Insurance, Disaster Insurance Guidebook (PDF, undated).
Laws and bulletins change. Sources last checked October 16, 2026. General information, not legal or claims advice. For help with a claim, call the Department of Insurance at 800-927-4357.